In December 2024, the Office for National Statistics changed its mind about what a defined benefit pension is worth.
After the Government Actuary’s Department reviewed its method, the ONS switched the way it discounts a promised future pension back to a value today, used the new basis for its 2020 to 2022 wealth figures, and in July 2026 republished its 2018 to 2020 figures to match. The figures moved. As the statisticians put it themselves, there is “no single agreed method for calculating the present value” of a defined benefit claim.
If the national statistician needs an actuarial review to price one of these, some fuzziness in valuing your own is to be expected.
So this is the practical version: how to put a defensible number on a defined benefit pension so it can sit on your balance sheet, and why three reasonable methods will hand you three different figures. It assumes you’ve already decided a pension belongs in your net worth. If you’re not sure it does, start there and come back.
Why this one asset has no price tag
Most pensions people pay into today are defined contribution. You and your employer pay in, the money is invested, and there’s a pot with a live value you can read off a screen. Valuing it takes about ten seconds: log in, copy the number, done. It behaves like a Stocks and Shares ISA that you can’t touch yet.
A defined benefit pension, the final-salary and career-average kind still common across the public sector and older private schemes, works differently. What you own is a promise: a set income each year for the rest of your life once you retire, usually rising with inflation, with no balance attached. That’s why these pensions get dropped from net worth sums, and why the number, once estimated, tends to be far bigger than people expect. It also explains how pot-based pension averages by age can make a DB member look as if they have almost nothing.
You can put a value on a promise, as long as you accept from the start that the result is an estimate. Here are three ways to do it, from least effort to most baggage.
Method one: the number your scheme already hands you
Your annual benefit statement is the first place to look, and for a lot of people it’s enough. A defined benefit statement tells you the pension you’ve built up so far, expressed as an income: “a pension of £8,400 a year, payable from 65.” That accrued figure is the raw material for everything else.
Some schemes go further and print a capital value or a “pension equivalent” alongside it. If yours does, that’s a number produced by the scheme’s own actuaries on the scheme’s own assumptions, which makes it a reasonable line to use, as long as you note where it came from. Not every statement includes one, and the ones that do rarely explain the assumptions behind it. When the statement gives you only an annual income, you need a way to turn that income into a lump sum. That’s method two.
Method two: the rule-of-thumb multiple
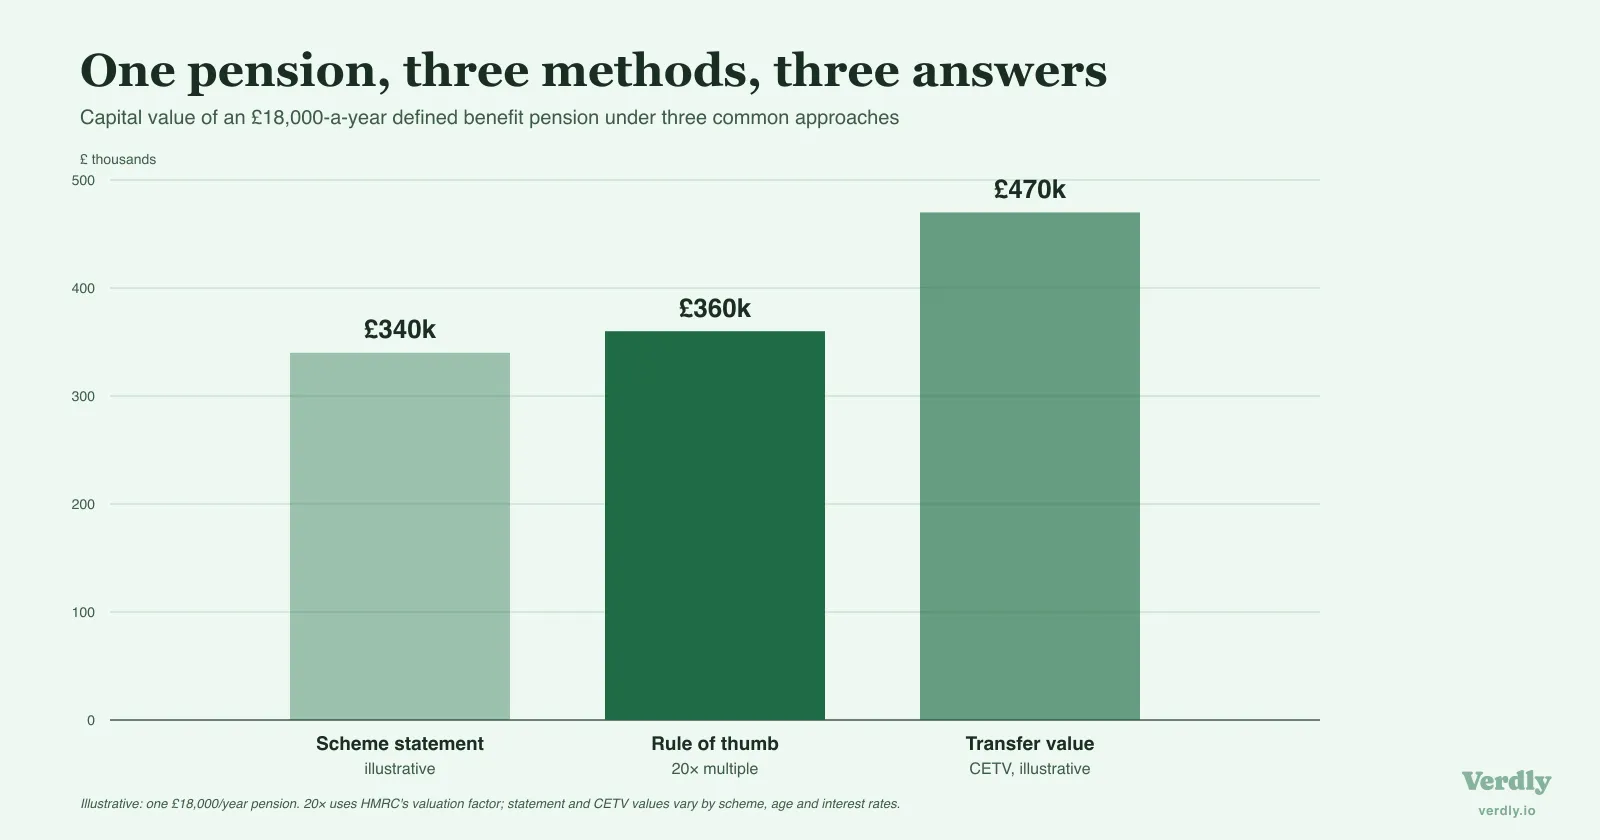
The quickest way to turn a promised income into a capital figure is to multiply it. The common shorthand is around twenty times the annual pension, and it has a source: HMRC has long used a valuation factor of 20 to value defined benefit entitlements for its own tax purposes, so a pension paying £18,000 a year lands at roughly £360,000 of wealth.
Twenty is a blunt instrument, though. The real cost of buying a guaranteed, inflation-linked income shifts with interest rates and with your age, and a younger person’s promise is worth less today than the same promise to someone about to retire, because the money is further away. Whatever figure comes out is an estimate with a wide margin; the multiple earns its place by being quick, transparent and easy to repeat next year.
Method three: the transfer value
The third figure is the most concrete. A defined benefit scheme will, on request, quote a cash equivalent transfer value: the sum it would move out of the scheme on your behalf if you gave up the pension. It’s backed by real money and often large, sometimes well above twenty times the annual income.
It’s also the figure to handle with the most care. A transfer value is offer-specific and time-limited, it swings hard with interest rates, and it exists for a different purpose than net worth tracking. Verdly publishes for education, not financial advice; a transfer value is a valuation reference here, nothing more, and decisions about a defined benefit pension are exactly the kind you’d take to a regulated adviser. Reading a CETV as “what my pension is worth today” is defensible for a balance sheet. Treating it as money to move is a separate decision, and one this piece does not make.
If your scheme has sent you a transfer value recently, it’s a legitimate data point, as long as the label says what it is.
Why the three numbers disagree
Line up all three for the same pension and they won’t match. The statement’s capital value, the twenty-times shorthand, and the transfer value can sit thousands of pounds apart. The gap between them is the discount rate doing its work.
Every one of these methods has to answer the same question: how much is £1 of pension income in thirty years’ time worth today? The tool for that is a discount rate, and the ONS is direct about how much rides on it, calling the choice “a very important modelling decision” because for payments far in the future “the present value is very sensitive to the rate used.”
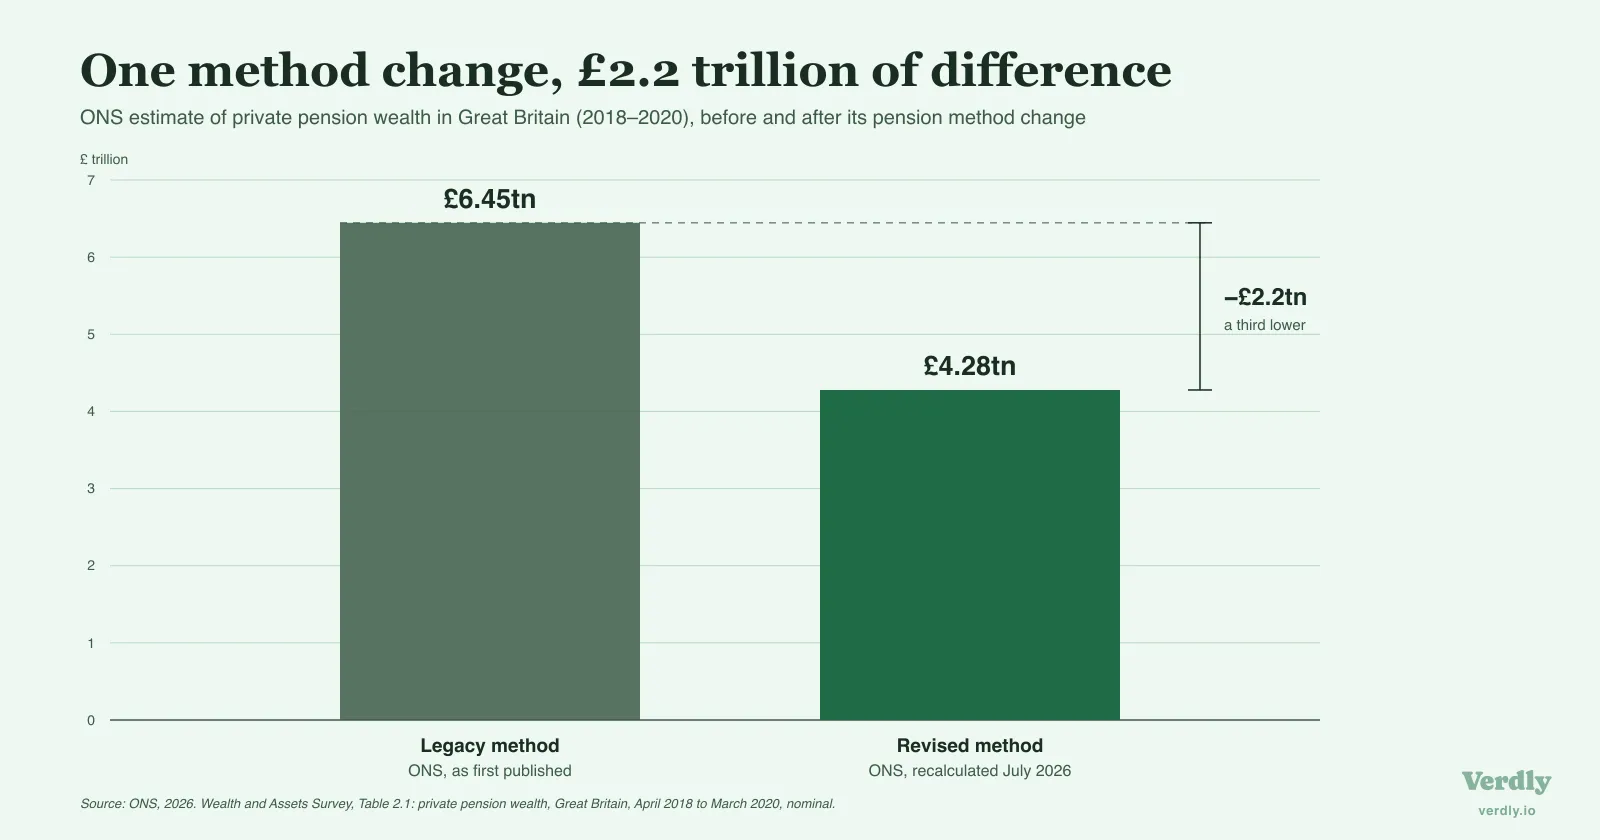
When the ONS recalculated its 2018 to 2020 figures on the new method, its estimate of private pension wealth in Great Britain fell by more than a third, from around £6.4 trillion to around £4.3 trillion, with the same pensions and the same survey responses. Nor is the lower figure settled: the Institute for Fiscal Studies argues the updated approach understated these promises while interest rates were ultra-low, and its own method puts mean household pension wealth for 2020 to 2022 at roughly twice the ONS estimate. Every figure for a defined benefit pension is a value under an assumption, and when the assumption changes, so does the number.
Putting a number on it without kidding yourself
The people whose job is to value these pensions can’t agree on a single figure, so a personal estimate has room to be approximate. Consistency from one year to the next matters more.
Pick one method and stick with it. The twenty-times shorthand keeps the effort low: pull the annual pension off your statement, apply a sensible multiple, write down that you used it. Log it as its own line rather than folding it into “savings,” because a promise of future income behaves very differently from cash, and separating the two keeps what net worth measures clear. Then leave it mostly alone: a defined benefit pension changes slowly, and the trend over several years says more than any single month’s figure.
The ONS keeps working on the method for the same reason a personal balance sheet needs the line: for a lot of households a defined benefit pension is the largest thing they own, and leaving it blank records that asset as zero. Put the pension on the page with the method noted beside it, and track it alongside everything else so each new valuation can be set against the last.
Last reviewed 14 September 2026.